IMGC Mortgage Guarantee: Benefits, Charges & How It Helps Home Loan Borrowers
Buying a home is a big dream for most families. But getting the required home loan can sometimes be difficult because of income, existing EMIs, credit profile, down payment or other eligibility conditions.
You may have heard about IMGC mortgage guarantee while discussing a home loan.
But what is IMGC?
How does it help a home buyer?
What are the charges?
And most importantly, how does the borrower benefit?
Let’s understand everything in simple language.
What Is IMGC?
IMGC stands for India Mortgage Guarantee Corporation.
IMGC is a mortgage guarantee company that works with banks and housing finance companies.
The simple idea is:
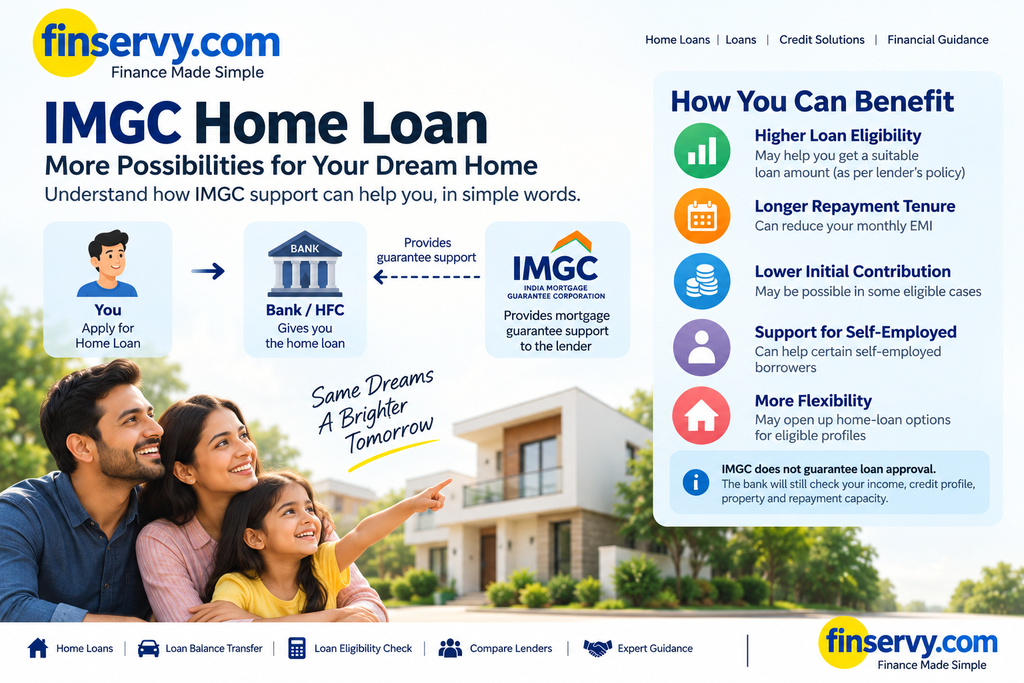
You apply for a home loan → The bank/HFC gives you the loan → IMGC provides mortgage guarantee support to the lender for eligible loans.
IMGC does not directly give the home loan to you.
The bank or housing finance company still decides whether your loan can be approved.
IMGC says it is India’s first mortgage guarantee company and has helped more than 1.75 lakh households through mortgage guarantees.
What Is a Mortgage Guarantee?
A mortgage guarantee is basically an additional layer of protection for the lender.
For certain home loans, especially loans involving a lower down payment or specific borrower profiles, the lender may have higher credit risk.
A mortgage guarantee helps the lender manage part of that risk.
In simple words:
IMGC supports the lender, and this can help the lender offer suitable home-loan options to eligible borrowers.
How Can a Borrower Benefit From IMGC?
This is the most important question.
The borrower does not receive money directly from IMGC.
Instead, the benefit can come through the loan structure offered by the lender.
According to IMGC, mortgage guarantee-backed home loans can help eligible borrowers with:
1. Higher Loan Eligibility
Mortgage guarantee support can help lenders offer a higher eligible loan amount in certain cases.
This can be useful when your income and repayment capacity are suitable, but the normal loan eligibility may not be enough for the property you want to buy.
2. Lower Down Payment in Eligible Cases
A mortgage guarantee can help some borrowers buy a home with a lower initial contribution.
This can be especially useful for first-time home buyers who have limited savings.
IMGC says mortgage guarantees can help families buy homes with a lower down payment and keep some of their savings available for other needs.
However, the actual down payment depends on the lender, property and applicable rules.
3. Longer Loan Tenure
In some eligible cases, mortgage guarantee support can help lenders offer a longer repayment period.
A longer tenure can reduce the monthly EMI.
For example, if your loan is spread over a longer period, your monthly payment may become easier to manage.
However, remember that a longer tenure can also mean paying more total interest over the life of the loan.
IMGC states that its programs can support home loans with repayment periods of up to 30 years, subject to the applicable lender and product conditions.
4. Help for Certain Self-Employed Borrowers
Self-employed people sometimes have income that is more difficult to assess than a fixed monthly salary.
IMGC says its mortgage guarantee programs can support lenders in reaching certain self-employed and other borrower segments where income requires detailed assessment.
This does not mean every self-employed applicant will qualify.
The lender will still assess the borrower’s financial profile.
5. Less Dependence on Personal or Gold Loans
Sometimes, a person may take a personal loan or gold loan to arrange the money needed for buying a property.
These loans can be expensive compared with a home loan.
IMGC says enhanced eligibility through mortgage guarantee-backed home loans can reduce dependence on such expensive funding sources in eligible cases.
What Are IMGC Charges?
There can be a mortgage guarantee fee.
But there is no single fixed charge that applies to every borrower.
According to IMGC, the fee can depend on factors such as:
- Down payment
- Credit score
- Type of mortgage
- Amount of guarantee coverage
So, don’t assume that every IMGC-backed home loan will have the same charge.
Who Pays the IMGC Fee?
This depends on the type of mortgage guarantee arrangement.
For some retail loan products, the guarantee fee is usually built into the borrower’s EMI.
For portfolio arrangements, the lender may bear the fee or the arrangement may be different.
Therefore, before accepting your home loan, ask the lender:
“Is there an IMGC guarantee fee in my loan? How much is it, and how will I pay it?”
That one question can save you from surprises later.
Does Paying the IMGC Charge Give Me a Benefit?
Potentially, yes, but the benefit is not a cash payment from IMGC.
The possible benefit is that the mortgage guarantee can help the lender offer a suitable loan structure.
For example, depending on the lender’s program, it may help with:
Higher eligibility + longer tenure + lower initial contribution + access to suitable loan options
The actual benefit depends on your profile and the lender’s policy.
Is IMGC the Same as Home Insurance?
No.
They are completely different.
Home insurance protects the homeowner/property against covered risks such as fire, theft or other insured events.
Mortgage guarantee is mainly designed to protect the lending institution against certain credit-default risks.
IMGC clearly states that mortgage guarantee and homeowner insurance are not the same thing.
Does IMGC Guarantee Home Loan Approval?
No.
This is very important.
Having an IMGC-supported loan does not mean that your home loan will automatically be approved.
The lender will still check:
- Income
- Credit history
- Existing EMIs
- Bank statements
- Property details
- Repayment capacity
- Required documents
- Its own lending policy
IMGC itself does not sanction or disburse home loans. Its role is to provide mortgage guarantees to lending institutions.
Does the Borrower Still Have to Repay the Loan?
Yes.
A mortgage guarantee does not mean that your home loan becomes free or that your repayment responsibility disappears.
You still have to pay your EMI according to your loan agreement.
The guarantee is primarily a risk-management arrangement between the lender and IMGC.
Simple Example of an IMGC Home Loan
Let’s say you want to buy a house worth ₹50 lakh.
You approach a bank for a home loan.
The bank checks your:
Income + Credit Profile + Existing EMIs + Property + Repayment Capacity
Suppose the loan is eligible under the bank’s mortgage guarantee program.
The bank may use IMGC’s guarantee support as an additional risk-management tool.
This may help the bank structure the loan for you under the applicable program.
But the final loan amount, interest rate, tenure and down payment will still depend on the lender’s assessment.
Is IMGC Useful for First-Time Home Buyers?
It can be useful in eligible cases.
First-time buyers often face one major problem:
They may have enough income to pay an EMI but not enough savings for a large initial contribution.
IMGC says mortgage guarantees can help eligible buyers with lower down payments and earlier access to home ownership.
IMGC Home Loan: Quick Summary
| Question | Simple Answer |
|---|---|
| What is IMGC? | India Mortgage Guarantee Corporation |
| Does IMGC give the home loan? | No |
| Who gives the home loan? | Bank or housing finance company |
| What does IMGC provide? | Mortgage guarantee support to the lender |
| Can it help with loan eligibility? | It may, depending on the lender and program |
| Can it help with lower down payment? | It may in eligible cases |
| Can it support longer tenure? | Yes, under applicable programs |
| Can self-employed borrowers benefit? | Some may, depending on eligibility |
| Is there an IMGC charge? | A guarantee fee may apply |
| Is the fee the same for everyone? | No |
| Does IMGC guarantee loan approval? | No |
| Does the borrower still repay the loan? | Yes |
Final Word
IMGC mortgage guarantee is not another type of home loan.
It is a guarantee arrangement that can help lenders manage credit risk on eligible home loans.
For borrowers, the possible benefit is better access to suitable loan structures, which may include higher eligibility, longer repayment tenure or lower initial contribution in eligible cases.
But every home loan is different.
Before accepting a loan, always check:
Loan amount + Interest rate + EMI + Tenure + Down payment + Processing fee + IMGC guarantee fee + Other applicable charges
At Finservy, we help customers understand home-loan options and the costs involved before they make a decision.
If you are planning to buy a home, transfer your existing home loan or check your home-loan eligibility, visit:
Frequently Asked Questions
Is IMGC a bank?
No. IMGC is a mortgage guarantee company.
Can IMGC directly give me a home loan?
No. The loan is provided by a participating bank or housing finance company.
Does IMGC guarantee my loan approval?
No. The lender makes the final credit decision.
What is the IMGC charge?
A mortgage guarantee fee may apply. The amount can vary based on factors such as down payment, credit score, mortgage type and guarantee coverage.
Can IMGC help me get a higher loan amount?
It may help eligible borrowers obtain higher loan eligibility under certain lender programs.
Can IMGC help reduce my EMI?
A longer repayment tenure may reduce the monthly EMI, where such a structure is available and approved by the lender.
Can self-employed people get IMGC-supported home loans?
Certain lender programs may support self-employed borrowers, subject to the lender’s eligibility criteria.
Do I still need to repay my home loan?
Yes. The mortgage guarantee does not remove your responsibility to repay the loan.
Disclaimer: IMGC availability, guarantee fee, eligibility, loan amount, interest rate, tenure and other terms depend on the participating lender, borrower profile, property and applicable policies. This article is for general awareness and does not guarantee loan approval.