Savings Account vs Current Account: Difference, Features, Conditions & Which Account Do You Need?
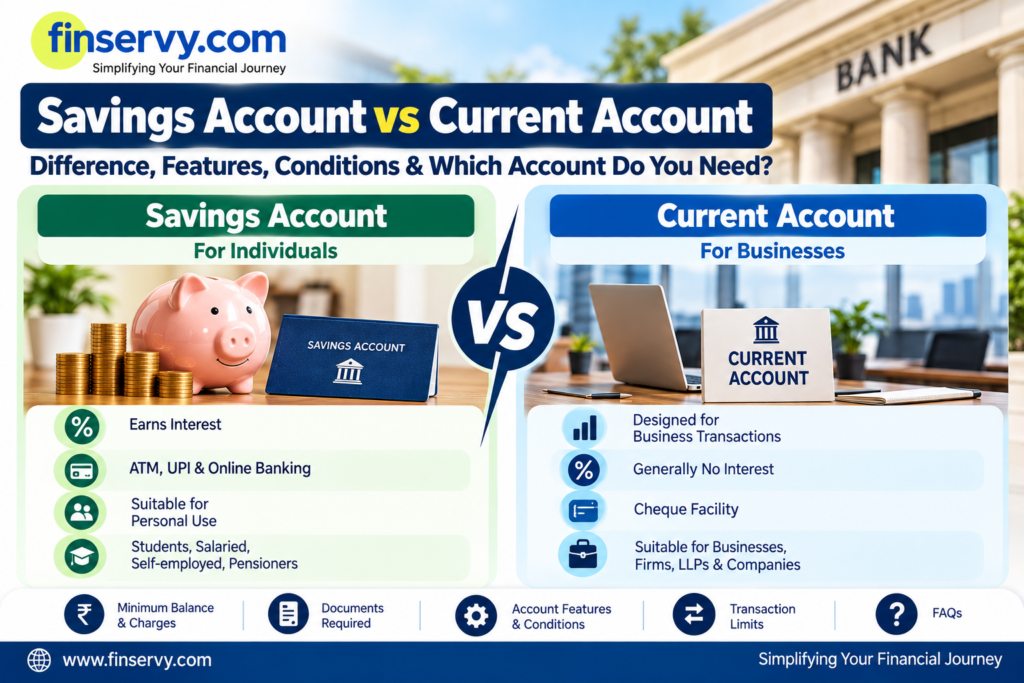
Savings Account vs Current Account: Difference, Features, Conditions & Which Account Do You Need?
When you open a bank account, one common question is: Should I open a Savings Account or a Current Account?
Both accounts are useful, but they are designed for different purposes.
A Savings Account is generally meant for individuals who want to keep their money safely in a bank and earn interest on their balance.
A Current Account is generally designed for businesses, firms, companies and professionals who need frequent transactions for their business activities.
In this blog, let us understand the difference between Savings Account and Current Account, their features, conditions, charges and who should choose each type.
What Is a Savings Account?
A Savings Account is a bank account mainly used for saving and managing personal money.
You can deposit money, withdraw money, use UPI, ATM/debit cards and online banking, and receive payments into the account.
Banks generally pay interest on the balance maintained in a savings account. The interest rate and other conditions depend on the bank and the type of savings account.
Who Can Open a Savings Account?
A Savings Account can generally be opened by:
- Salaried employees
- Self-employed individuals
- Students
- Pensioners
- Homemakers
- Individuals with regular income
- Minors through applicable account arrangements
- Other eligible individuals
The exact eligibility depends on the bank and account type.
What Is a Current Account?
A Current Account is generally used for regular business transactions.
Businesses may receive payments from customers, make payments to suppliers, issue cheques and carry out frequent banking transactions through a current account.
Current accounts are commonly used by:
- Sole proprietorships
- Partnership firms
- LLPs
- Private limited companies
- Public limited companies
- Shops and businesses
- Professionals
- Other eligible business entities
Unlike a typical savings account, a current account generally does not offer interest on the balance, although specific products and conditions can vary between banks.
Savings Account vs Current Account
Here is a simple comparison:
| Feature | Savings Account | Current Account |
|---|---|---|
| Main purpose | Personal savings and banking | Business transactions |
| Usually suitable for | Individuals | Businesses and professionals |
| Interest | Generally paid | Generally not paid |
| Transaction requirement | Normal/personal transactions | Frequent business transactions |
| Minimum balance | Depends on account | Depends on account |
| UPI & online banking | Usually available | Usually available |
| Debit card | Usually available | Usually available depending on account |
| Cheque facility | Usually available | Usually available |
| Cash transactions | Subject to bank/account limits | Designed for business requirements, subject to limits |
| Overdraft facility | May be available for eligible customers | May be available depending on eligibility |
| Account opening documents | KYC and applicable documents | KYC plus business/entity documents |
Important: Banking rules, charges, transaction limits and minimum balance requirements vary from bank to bank and from one account variant to another.
Savings Account: Important Features
A Savings Account may provide several useful banking facilities.
1. Interest on Balance
Banks generally pay interest on eligible savings account balances.
The rate can vary depending on the bank and account type.
2. ATM/Debit Card
Customers can generally use a debit card for ATM withdrawals, purchases and other permitted transactions.
3. UPI Payments
Savings accounts can generally be linked to UPI for digital payments.
4. Internet and Mobile Banking
Customers can use digital banking services to:
- Transfer money
- Check account balance
- Download statements
- Pay bills
- Manage beneficiaries
- Make other permitted banking transactions
5. Nomination Facility
Eligible customers can generally add a nominee to their bank account.
6. Different Types of Savings Accounts
Banks may offer different savings account variants, such as:
- Regular Savings Account
- Salary Account
- Senior Citizen Savings Account
- Student Account
- Basic Savings Bank Deposit Account
- Digital Savings Account
- Other specialised savings products
The features and conditions can differ significantly.
Current Account: Important Features
Current Accounts are designed around business banking requirements.
1. Frequent Transactions
Businesses may need to receive and make payments regularly. Current accounts are structured to support such business banking activity, subject to the applicable account limits and charges.
2. Business Payments
A current account can be used for payments to:
- Suppliers
- Employees
- Vendors
- Service providers
- Government authorities
- Other business-related recipients
3. Cheque Facility
Businesses may use cheque facilities for business payments, subject to the account’s terms.
4. Cash Deposit Facility
Businesses that handle cash may need higher cash deposit limits than typical personal banking needs.
However, cash deposit limits and charges vary by bank and account type.
5. Overdraft Facility
Some current accounts may provide an overdraft facility to eligible customers.
An overdraft is a facility that may allow an eligible account holder to withdraw or use funds beyond the available account balance, within an approved limit.
It is important to understand the interest, fees, security requirements and repayment conditions before using such a facility.
Minimum Balance: What Should You Know?
One important condition before opening a bank account is the minimum balance requirement.
Some accounts may require the customer to maintain a specified balance.
If the required balance is not maintained, the bank may apply charges according to the account terms.
However, not every account has the same requirement.
Some accounts may have:
- Zero balance requirements
- Low minimum balance requirements
- Monthly average balance requirements
- Quarterly average balance requirements
- Higher balance requirements for premium accounts
Therefore, always check the bank’s current Schedule of Charges and account terms before opening an account.
Savings Account Conditions You Should Check
Before opening a Savings Account, check:
1. Minimum Balance
Understand whether the account requires a minimum or average balance.
2. Interest Rate
Check the applicable interest rate and how interest is calculated and credited.
3. ATM/Debit Card Charges
Check whether there are annual card charges or other applicable fees.
4. ATM Transaction Limits
Banks may have limits on free ATM transactions and may charge for transactions beyond applicable limits.
5. Cash Deposit Limits
Check the permitted cash deposit limits and any applicable charges.
6. Account Closure Charges
Understand whether account closure charges apply.
7. Digital Banking Facilities
Check the availability and charges, if any, for internet banking, mobile banking and other services.
Current Account Conditions You Should Check
Business owners should pay particular attention to:
1. Minimum or Average Balance
Current accounts can have different balance requirements depending on the account variant.
2. Cash Deposit Limits
If your business receives substantial cash, check the permitted cash deposit limit and applicable charges.
3. Cash Withdrawal Limits
Understand the permitted cash withdrawal limits and charges.
4. Transaction Charges
Some current accounts may have charges based on transaction volume or the type of transaction.
5. Cheque Charges
Check applicable charges for cheque books, cheque processing and other related services.
6. NEFT/RTGS/IMPS and Other Charges
Review the bank’s current tariff for applicable digital and fund-transfer services.
7. Overdraft Terms
If you need an overdraft facility, understand the interest rate, approved limit, security requirements and other conditions.
Documents Required for a Savings Account
For an individual Savings Account, banks generally require KYC documents.
Common documents may include:
- PAN or Form 60, as applicable
- Aadhaar or another officially valid document
- Address proof where required
- Passport-size photograph, where applicable
- Mobile number
- Other documents required by the bank
The exact requirements can vary depending on the customer and account type.
Documents Required for a Current Account
Current Account documentation depends on the type of business.
For example, a bank may ask for:
- PAN
- Identity and address proof
- Business address proof
- Business registration documents
- GST registration, where applicable
- Partnership deed for partnership firms
- LLP incorporation documents for LLPs
- Certificate of incorporation and company documents for companies
- Board resolution, where applicable
- Beneficial ownership details
- Other KYC and business-related documents
The exact list depends on the business structure and the bank’s KYC requirements.
Can You Use a Savings Account for Business?
This is an important point.
A Savings Account is generally intended for personal banking.
If you are running a business and carrying out regular business transactions, a Current Account may be more appropriate, depending on your business structure and banking requirements.
Using the wrong type of account can create practical problems if the transaction pattern does not match the account’s permitted usage.
Always check the bank’s account terms before using a personal account for business transactions.
Can a Business Owner Have a Savings Account?
Yes.
A business owner can have a personal Savings Account for personal expenses and a Current Account for business transactions.
For example:
Personal expenses → Savings Account
Business receipts and payments → Current Account
Keeping personal and business transactions separate can also make financial record-keeping easier.
Savings Account or Current Account: Which One Do You Need?
The answer depends mainly on why you need the account.
If you are an individual:
A Savings Account may generally meet your requirements for:
- Saving money
- Receiving salary
- Personal expenses
- UPI payments
- Online shopping
- Utility payments
- Regular personal banking
If you run a business:
A Current Account may generally be more suitable for:
- Business collections
- Supplier payments
- Regular business transactions
- Business-related cheque payments
- Managing business cash flows
The right choice ultimately depends on your transaction requirements, account conditions and the bank’s product terms.
Important: Read the Account Terms Before Opening
Before opening any bank account, don’t look only at the interest rate or minimum balance.
Check the complete list of applicable conditions, including:
- Minimum balance
- Cash deposit limits
- Cash withdrawal limits
- ATM charges
- Debit card charges
- Cheque book charges
- Fund transfer charges
- Non-maintenance charges
- Account closure charges
- Service charges
- Transaction limits
- Overdraft terms, if applicable
Bank charges and conditions can change. Always verify the latest information directly with the concerned bank before opening an account.
Common Mistakes Customers Make
Mistake 1: Choosing an account only because of a low minimum balance
A low minimum balance does not necessarily mean the account is the most suitable for your needs.
Mistake 2: Ignoring transaction charges
Frequent transactions can make transaction-related charges important.
Mistake 3: Using a personal account for business
Business owners should check whether their account type permits the intended usage.
Mistake 4: Not checking cash deposit charges
This is especially important for businesses that handle significant cash.
Mistake 5: Not reading the Schedule of Charges
Always check the latest charges before opening an account.
Frequently Asked Questions
Is a Savings Account better than a Current Account?
They serve different purposes. A Savings Account is generally designed for personal banking and saving, while a Current Account is generally designed for business transactions.
Does a Current Account earn interest?
A typical current account generally does not pay interest on the balance, but account features can vary. Check the specific bank’s terms.
Can I use UPI with a Current Account?
UPI availability depends on the bank, account type and applicable UPI/business banking support.
Can I open both Savings and Current Accounts?
Yes, an individual can have a personal Savings Account and a business Current Account, subject to the respective bank’s eligibility and account rules.
What is the minimum balance for a Savings Account?
There is no single minimum balance applicable to all Savings Accounts. It depends on the bank and account variant.
What is the minimum balance for a Current Account?
It varies by bank and account type. Some business accounts may require a higher balance than basic accounts.
Which account is suitable for a small business?
A Current Account is generally designed for business transactions, but the right account depends on the nature of the business, transaction volume and the bank’s terms.
Final Takeaway
A Savings Account is generally designed for personal banking and saving.
A Current Account is generally designed for businesses and frequent business transactions.
Before opening either account, don’t just ask, “What is the minimum balance?”
Also ask:
What are the transaction limits?
What are the charges?
What cash deposit limits apply?
What services are included?
What conditions apply to this particular account?
Choosing an account based on your actual banking needs can help you manage your money more efficiently.
Need Help Understanding Financial Products?
At Finservy, we simplify financial information so customers can understand their options before making financial decisions.
Visit finservy.com to explore our financial services and educational resources.
Finservy.com
Simplifying Your Financial Journey