Home Loan Take Over
Transfer Home Loan to reduce EMI and Interest Rates
Home Loan Takeover & Mortgage Loan Balance Transfer
Are you paying a high interest rate on your existing home loan or mortgage loan? A Home Loan Takeover or Balance Transfer may help you explore better interest rates, repayment terms, and suitable loan options from other banks or financial institutions.
At Finservy, we help you review your existing loan and explore suitable balance transfer options based on your financial profile, outstanding loan amount, repayment history, property details, and lender eligibility criteria. Our goal is to simplify the loan transfer journey with transparent guidance and assistance throughout the process.
What Is a Home Loan Takeover?
A Home Loan Takeover, also known as a Home Loan Balance Transfer, is a facility through which you transfer your outstanding home loan from your existing bank or financial institution to another lender.
The new lender evaluates your application, property documents, income, credit profile, and repayment history. If your application is approved, the new lender settles the eligible outstanding loan with your existing lender, and you continue repayments under the new loan agreement.
Depending on the interest rate, outstanding principal, remaining tenure, processing charges, and other applicable costs, a home loan takeover may help reduce your interest burden or provide more suitable repayment terms
Benefits of a Home Loan Balance Transfer
1. Explore Lower Interest Rates
If another lender offers a lower applicable interest rate, transferring your home loan may help reduce your interest costs. The actual benefit depends on your outstanding balance, remaining tenure, and transfer charges.
2. Potentially Reduce Your Monthly EMI
A lower interest rate or a revised repayment tenure may help reduce your monthly EMI. However, extending the tenure could increase the total interest paid over the life of the loan.
3. Review Your Loan Repayment Terms
A balance transfer gives you an opportunity to review your existing loan terms and compare them with offers available from other eligible lenders.
4. Explore Additional Funding Options
Some lenders may offer a top-up loan along with an eligible home loan balance transfer, subject to their policies, property valuation, repayment capacity, and credit assessment.
5. Get Guidance Throughout the Process
Finservy helps you understand available options, prepare the required documents, and navigate the application process with participating banks and financial institutions.
Mortgage Loan Balance Transfer: Can You Transfer a Loan Against Property?
Yes, an existing mortgage loan or Loan Against Property (LAP) may also be eligible for a balance transfer to another bank or financial institution.
If you have mortgaged your residential or commercial property to obtain a loan and are paying a high interest rate, you can explore transferring your outstanding loan to another eligible lender.
A Mortgage Loan Balance Transfer may offer an opportunity to review your interest rate, repayment tenure, and overall borrowing costs. The new lender will assess the property’s market value, outstanding loan amount, income, credit history, existing repayment obligations, and legal documentation before deciding on approval.
Depending on the lender’s policies and your eligibility, you may also be able to explore additional funding through a top-up facility. Approval, interest rates, loan amounts, and repayment terms are subject to the lender’s assessment.
At Finservy, we assist customers in exploring both Home Loan Takeover and Mortgage Loan Balance Transfer options through participating financial institutions.
Home Loan Takeover vs. Mortgage Loan Balance Transfer
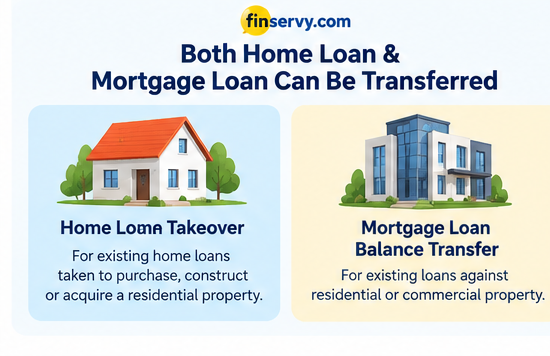
Both facilities involve transferring an eligible outstanding loan to another lender, but the purpose of the original loan differs.
Home Loan Takeover: Applies to an existing home loan taken to purchase, construct, or acquire a residential property, subject to the original loan terms.
Mortgage Loan Balance Transfer: Applies to an eligible loan secured against property, commonly known as a Loan Against Property, which may have been taken for business, personal, or other permitted financial needs.
The applicable interest rate, loan-to-value ratio, eligibility, documentation, and charges can differ between these facilities.
Who Can Apply for a Loan Balance Transfer?
You may explore a home loan takeover or mortgage loan balance transfer if you:
Have an existing home loan or Loan Against Property.
Have a satisfactory repayment track record, as required by the new lender.
Have a stable and verifiable source of income.
Meet the new lender’s credit score and eligibility requirements.
Can provide the necessary property, income, and existing loan documents.
Meet the new lender’s property valuation and legal requirements.
Eligibility varies by bank or financial institution. Meeting these general conditions does not guarantee loan approval.
Documents Required for Home Loan Takeover
The following documents may be required, depending on the lender and your profile:
PAN card and Aadhaar card or other accepted identity and address proof.
Latest salary slips or business income documents.
Bank statements for the period requested by the lender.
Existing home loan statement and repayment track record.
Sanction letter and existing loan agreement, where required.
Property documents and approved plans, as applicable.
Outstanding principal statement or foreclosure letter from the existing lender.
Additional documents requested during legal, technical, and credit verification.
For a mortgage loan balance transfer, the lender may require additional property title documents, mortgage-related records, valuation reports, and business financial documents.
Why Choose Finservy for Your Loan Takeover?
At Finservy, we understand that choosing the right loan is about more than just an interest rate. Processing charges, remaining tenure, repayment flexibility, and the overall cost of borrowing also matter.
We help you:
Explore suitable home loan and mortgage loan transfer options.
Compare eligible offers from participating lenders.
Understand potential EMI and interest cost differences.
Identify the documents required for your application.
Navigate the loan transfer process with professional assistance.
Our aim is to make your loan journey simpler with clear information, responsive support, and a focus on your financial requirements.
Frequently Asked Questions
1. What is a home loan takeover?
A home loan takeover is the transfer of an outstanding home loan from one lender to another, subject to the new lender’s approval and terms.
2. Can I transfer my home loan to another bank?
Yes. You may apply to transfer your existing home loan to another bank or financial institution, subject to eligibility, credit assessment, property verification, and lender policies.
3. Can a mortgage loan or Loan Against Property be transferred?
Yes. An eligible Loan Against Property may be transferred to another lender through a mortgage loan balance transfer, subject to the new lender’s terms and approval.
4. Will my EMI reduce after a balance transfer?
Your EMI may reduce if the new loan offers a lower interest rate or a suitable revised repayment tenure. The actual outcome depends on your loan balance, remaining tenure, charges, and the new lender’s terms.
5. Can I get a top-up loan with a balance transfer?
Some lenders offer top-up loans with eligible balance transfers. Approval depends on income, credit profile, outstanding loan, property value, and lender policies.
6. Are there charges for a home loan takeover?
Depending on the lender and loan type, charges may include processing fees, legal and technical verification fees, documentation expenses, and other applicable costs. Review all charges before making a decision.
7. How do I apply through Finservy?
Contact Finservy with your existing loan details. Our team can help you explore suitable options and guide you through the application requirements.
Explore Your Loan Transfer Options with Finservy
Don’t continue with your existing loan without reviewing the alternatives available to you. Explore a Home Loan Takeover or Mortgage Loan Balance Transfer with Finservy and understand whether switching lenders could benefit your financial plans.
Get in touch with Finservy today to discuss your existing loan and explore suitable balance transfer options.
Disclaimer: Finservy provides loan-related assistance and guidance. Loan approval, interest rates, eligibility, loan amounts, and terms are determined by the respective lending institution. A balance transfer may involve fees and other costs, so compare the total cost of the new loan with your existing loan before proceeding.